November 5, 2026
Orion's Lighting Growth Comes at a Cost
LED revenue surged 40%, but installation-heavy projects dragged down margins
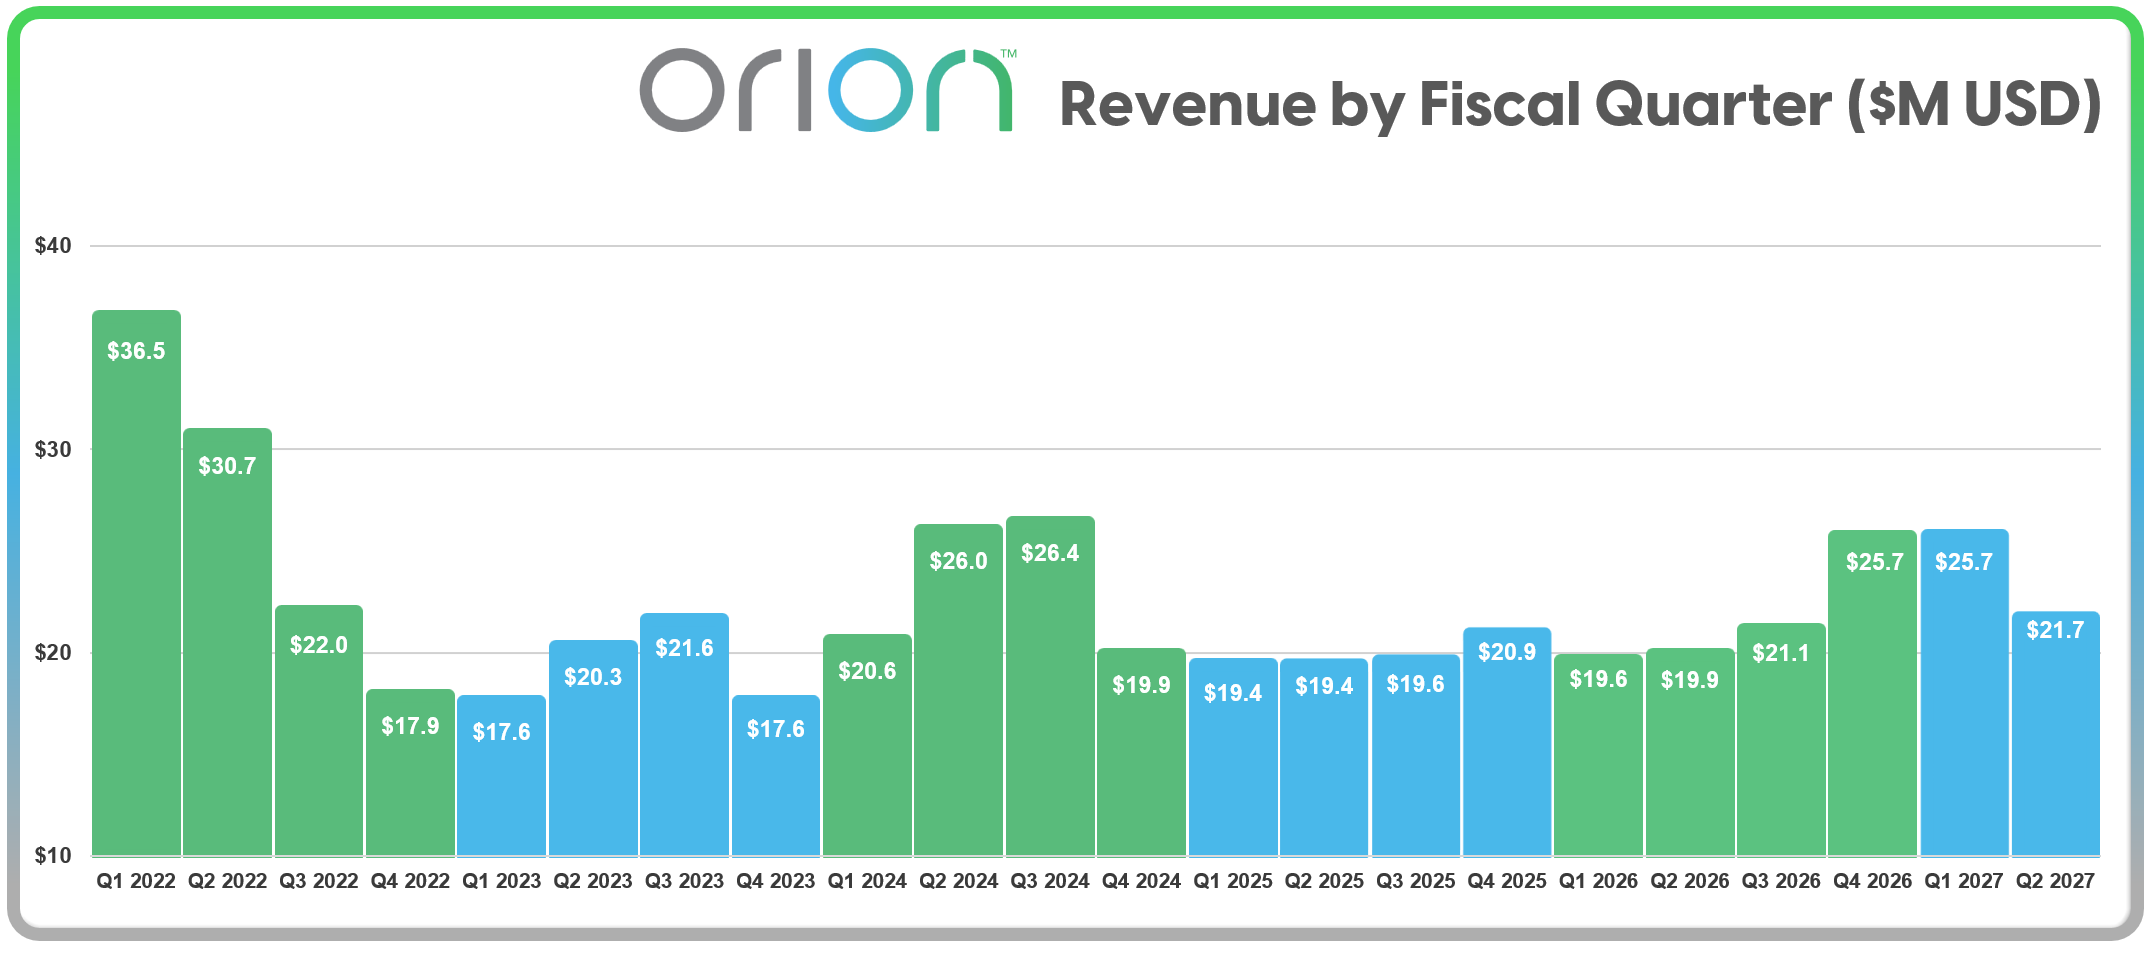
Orion Energy Systems warned in September that its fiscal second quarter would shrink from the first, and it did. Revenue for the quarter ended September 30 was $21.7 million, up 9% from a year earlier but down from $25.7 million in the first quarter. The more revealing number sat one line lower: gross margin fell to 28.7% from 31.0%.
The Manitowoc, Wisconsin company posted a net loss of $811,000, against $581,000 a year ago, and still stretched its run of positive adjusted EBITDA to eight straight quarters. The margin of victory was $12,000. The evidence this quarter is mixed, and full-year guidance now requires a second half that averages above Orion’s best quarter in years.
Lighting Grew. The Installs Ate the Margin.
For lighting people, the top line is good news. LED lighting revenue climbed 40% to $14.9 million and now makes up about 69% of Orion’s sales. Product revenue, however, rose only 5%, while service revenue rose 17% to $8.3 million even as EV charging and maintenance revenue both fell. That points to installation labor inside lighting projects.
Our income-statement arithmetic shows product gross margin improving to 34.9% from 31.5%, while service gross margin dropped to 18.6% from 30.1%. Orion attributes the overall decline to a mix shift in the lighting segment. Our split is consistent with that explanation, though it is our calculation rather than a company disclosure.
The practical read: Orion increasingly wins lighting work as a turnkey contractor, and contractor dollars carry thinner margins than fixture dollars.

The Streak, by the Numbers
Orion’s own reconciliation puts unadjusted EBITDA at negative $437,000. It turns positive only after adding back $446,000 of stock-based compensation, nearly triple the $157,000 of a year earlier. Without the $22,000 severance and $16,000 loss on fixed assets also added back, adjusted EBITDA would have been negative.
Every add-back fits Orion’s published non-GAAP definition, and first-half adjusted EBITDA totals $2.5 million. Nothing here looks improper. The cushion was simply thin. Operating expenses rose to $7.0 million from $6.4 million, with sales and marketing up 16% on higher commissions, according to the company.
The Back Half Has to Be the Best Half
In February we laid out the math Orion needed to stick the landing. It is back. First-half revenue was $47.4 million, so the reiterated $100 million to $102 million guidance requires $52.6 million to $54.6 million in the second half. That averages $26.3 million to $27.3 million per quarter, above the $25.7 million record Orion set in both the fourth quarter of fiscal 2026 and the first quarter of fiscal 2027. One strong quarter could offset a softer one.
There is support. A longtime retail customer committed to a $10 million to $15 million follow-on project for interior LED retrofits and IoT installations. Orion also landed a second multimillion-dollar MPHL2 order from the global hyperscaler behind June’s data-center win. In August we noted the data-center business was one customer. It still is, now with two orders, in a market we have tracked in our Acuity and Parameter coverage.
What is missing is a backlog number. June’s report put backlog at $30 million; this release gives nothing comparable.
Elsewhere: EV and Cash
The EV charging rebound we noted in August did not hold. EV revenue fell 41% to $2.8 million, about 13% of the total, which Orion ties to uncertainty over the scope, pace and funding of U.S. charging projects.
Cash moved the wrong way as well. Since March 31, accounts payable fell $5.2 million while the revolving credit facility rose to $5 million from $3 million, suggesting the company leaned more heavily on its credit line while paying down suppliers. First-half operating cash flow was negative $2.0 million, versus positive $1.3 million a year earlier. With $16.2 million in liquidity and the revolver extended to June 30, 2030, this is no survival story.
What Comes Next
Orion says significant projects for retailers, manufacturers, logistics providers, data centers and government customers will land in the third and fourth quarters. The revenue may well arrive. The mix will decide what it is worth: product-heavy deliveries carry fatter margins, while installation-heavy work looks a lot like this quarter.
The third quarter will start to settle it. For lighting people, the larger question may outlast the guidance: what kind of company Orion becomes if its fastest-growing work is also its least profitable.