Architecture Firms Face Deepening Business Slowdown
AIA reports falling billings, weakening contracts and growing caution among clients
THE MOST RECENT REPORT: October 21, 2026
WASHINGTON – Business conditions at architecture firms weakened further in September, according to the AIA/Deltek Architecture Billings Index (ABI). The ABI score fell to 44.7, down from August’s score of 47.2, marking the largest share of firms reporting declining billings since May. While inquiries for new projects increased modestly to 53.2 in September, the value of newly signed design contracts dropped to 43.7.
Billings remained weakest in the Northeast and continued to soften in the South, while firms in the Midwest and West reported stable conditions. Commercial and industrial firms posted modest growth for a second consecutive month, but billings declined again at institutional and multifamily residential firms, with the latter continuing to see significant weakening from earlier this year.
Despite softer demand, firms maintained a relatively healthy pipeline of future work. Average project backlogs stood at 6.2 months at the end of the third quarter, down from 6.6 months at the end of the first quarter. Backlogs remained stable at 8.1 months among large firms with annual billings of $5 million or more and at 8.0 months for firms specializing in institutional projects. Meanwhile, small firms with annual billings under $250,000 saw backlogs increase from 3.1 months to 3.8 months. Multifamily residential firms experienced the sharpest decline in backlogs, falling from 6.2 months in March to 4.8 months in September.
“This is an increasingly difficult environment for architecture firms,” said AIA Chief Economist Richard Branch. “Weakening billings are being compounded by a soft economy, challenging project financing and growing caution among clients. With fewer projects moving forward, there is little reason to expect a meaningful improvement in business conditions in the near term.”
Key ABI highlights for September include:
- Regional averages: West (50.7); Midwest (50.6); South (43.1); Northeast (39.1);
- Sector index breakdown: commercial/industrial (50.9); institutional (47.6); multifamily residential (42.9); mixed practice (firms that do not have at least half of their billings in any one other category) (41.5)
- Project inquiries index: 53.2
- Design contracts index: 43.7
Regional and sector categories are measured as three-month moving averages and may not align with the national score.
Inside Lighting strives to accurately report certain data on the day it is reported by the AIA, but updates to past data with new three-month rolling averages might not be made. For official and most current reports, refer to the AIA ABI numbers. All ABI data is sourced from the AIA.

Interpreting the ABI:
The Architecture Billings Index (ABI) is a leading economic indicator of construction activity. It is produced by the American Institute of Architects (AIA) and it reflects the approximate nine-to-twelve month lead time between architecture billings and construction spending.
The ABI is based on a monthly survey of architecture firms that asks respondents to rate the level of their billings (or the amount of new design contracts) as either "increase," "decrease," or "no change" from the previous month. The results are then compiled into an index, where a score above 50 indicates an increase in billings, and a score below 50 indicates a decrease in billings.
The ABI is widely used in the construction industry, as well as by economists and analysts, to track the health of the construction market and to forecast future building activity. It is considered a leading economic indicator because changes in architecture billings often precede changes in overall economic activity, such as employment and GDP.
The ABI provides a snapshot of the demand for design services as well as an indication of the near-term outlook for the construction industry.
The survey panel asks participating architectural firms whether billings increased, decreased or stayed the same in the month that just ended. According to the proportion of respondents choosing each option, a score is generated, which represents an index value for each month.
- An index score of 50 indicates no change in firm billings versus the previous month.
- A score above 50 indicates an increase in firm billings versus the previous month.
- A score below 50 indicates an decrease in firm billings versus the previous month.
- NOTE: Index numbers cited for the last three reported months are preliminary.
- The regional and sector categories are calculated as a 3-month moving average, whereas the national index, design contracts and inquiries are monthly numbers.
Source: The American Institute of Architects (AIA)
National Architecture Billings Index
Source: The American Institute of Architects (AIA)
RELATED: Historical ABI Data 2008 - 2022 »
Don’t miss the next big ABI update…Click here to subscribe to the inside.lighting InfoLetter |
Regional Architecture Billings Index
(Three month rolling average)
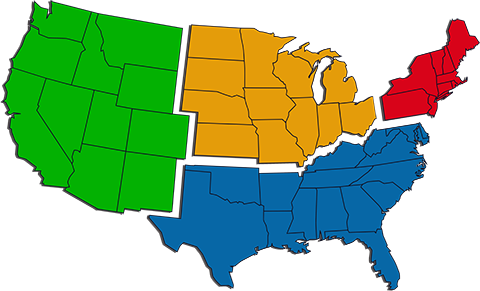
Source: The American Institute of Architects (AIA)
Sector-Specific Architecture Billings Index
Three-month rolling average
Commercial/Industrial
Buildings related to commerce and industry. Office space, banks, retail, factories, etc.
Institutional
Schools, civic/government buildings, museums, hospitals, etc.
Multifamily Residential
Town homes, apartment complexes, condominiums, etc.
Mixed Practice
Firms that do not have at least half of their billings in any one other category.

Source: The American Institute of Architects (AIA)
Architecture Billings Index® is a registered trademark of The American Institute of Architects
Don’t miss the next big ABI update…Click here to subscribe to the inside.lighting InfoLetter |